Workwear Market Trends 2026: Brand and Retailer Sales Data Reveal a Shift Toward Premium and Casual
The U.S. workwear market is shifting in 2026. Trailing 12-month sales data shows premium products outpacing value and mid-market tiers, established workwear brands losing share to casual retailers, and style-credible footwear brands holding loyal customers even as e-commerce grows. Here's where demand is heading.
Key Takeaways
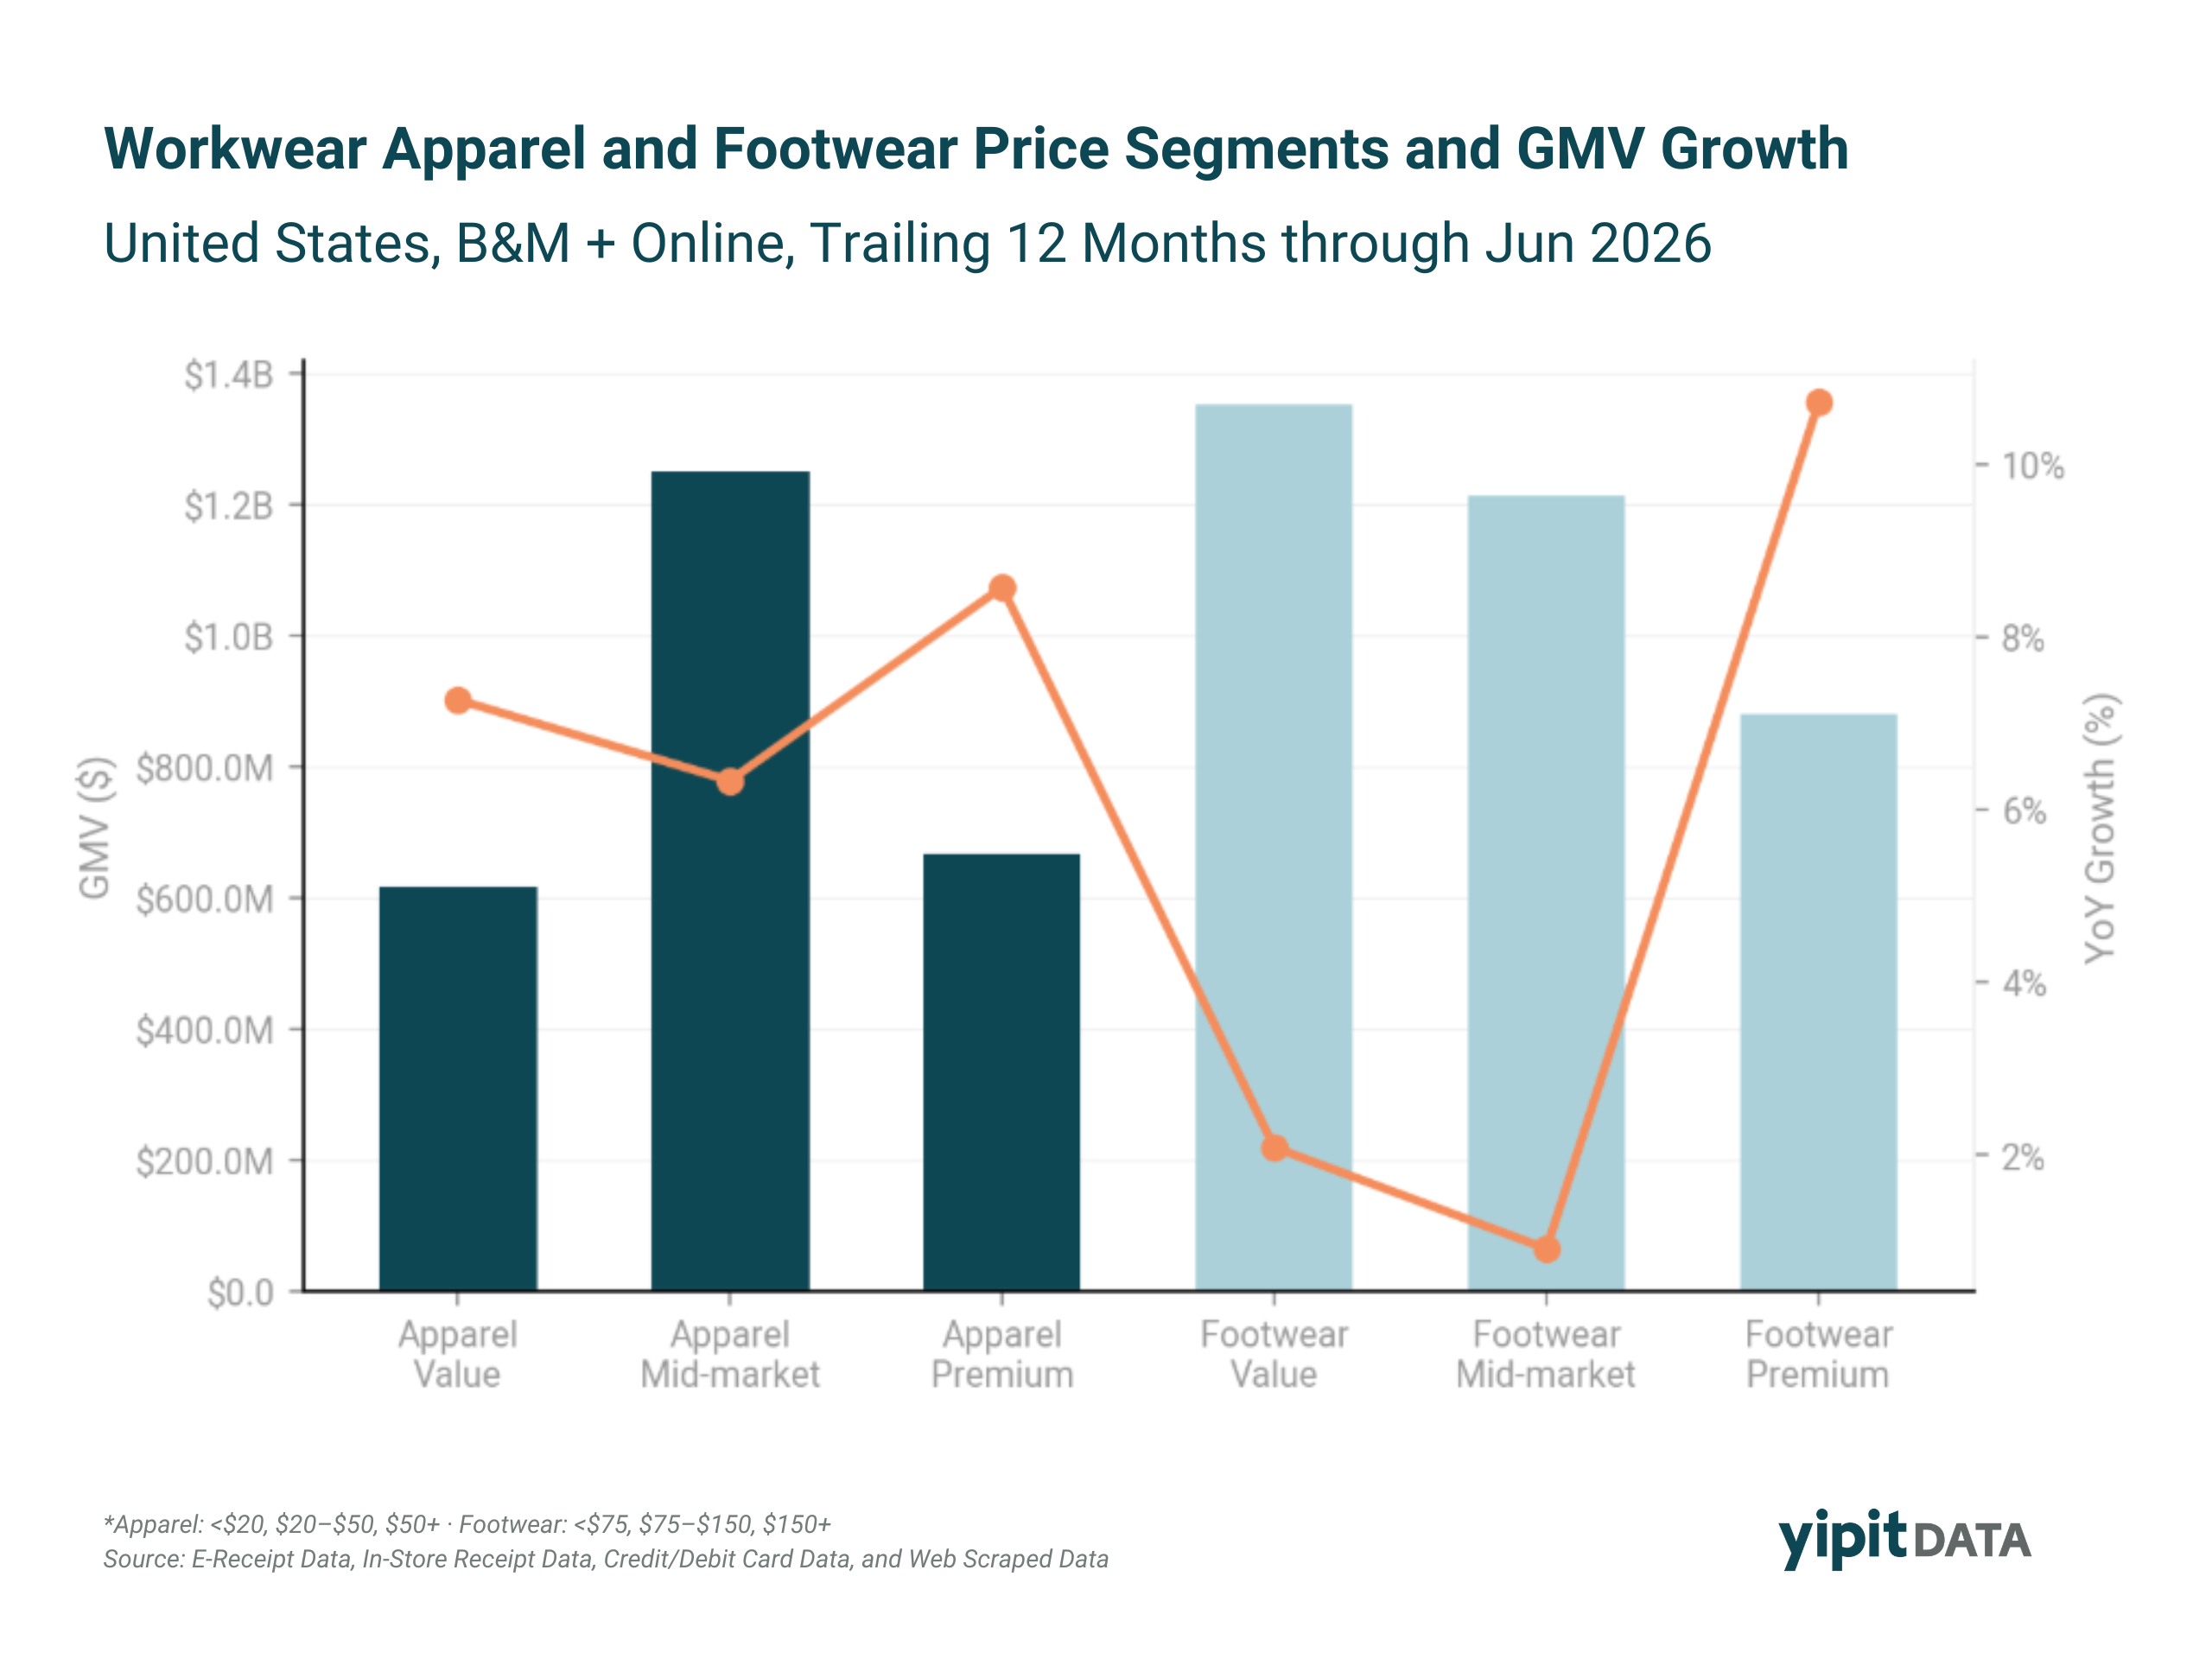
- Premium pricing is outpacing value and mid-market tiers across workwear apparel and footwear, with the trend most pronounced in footwear over the trailing 12 months through June 2026.
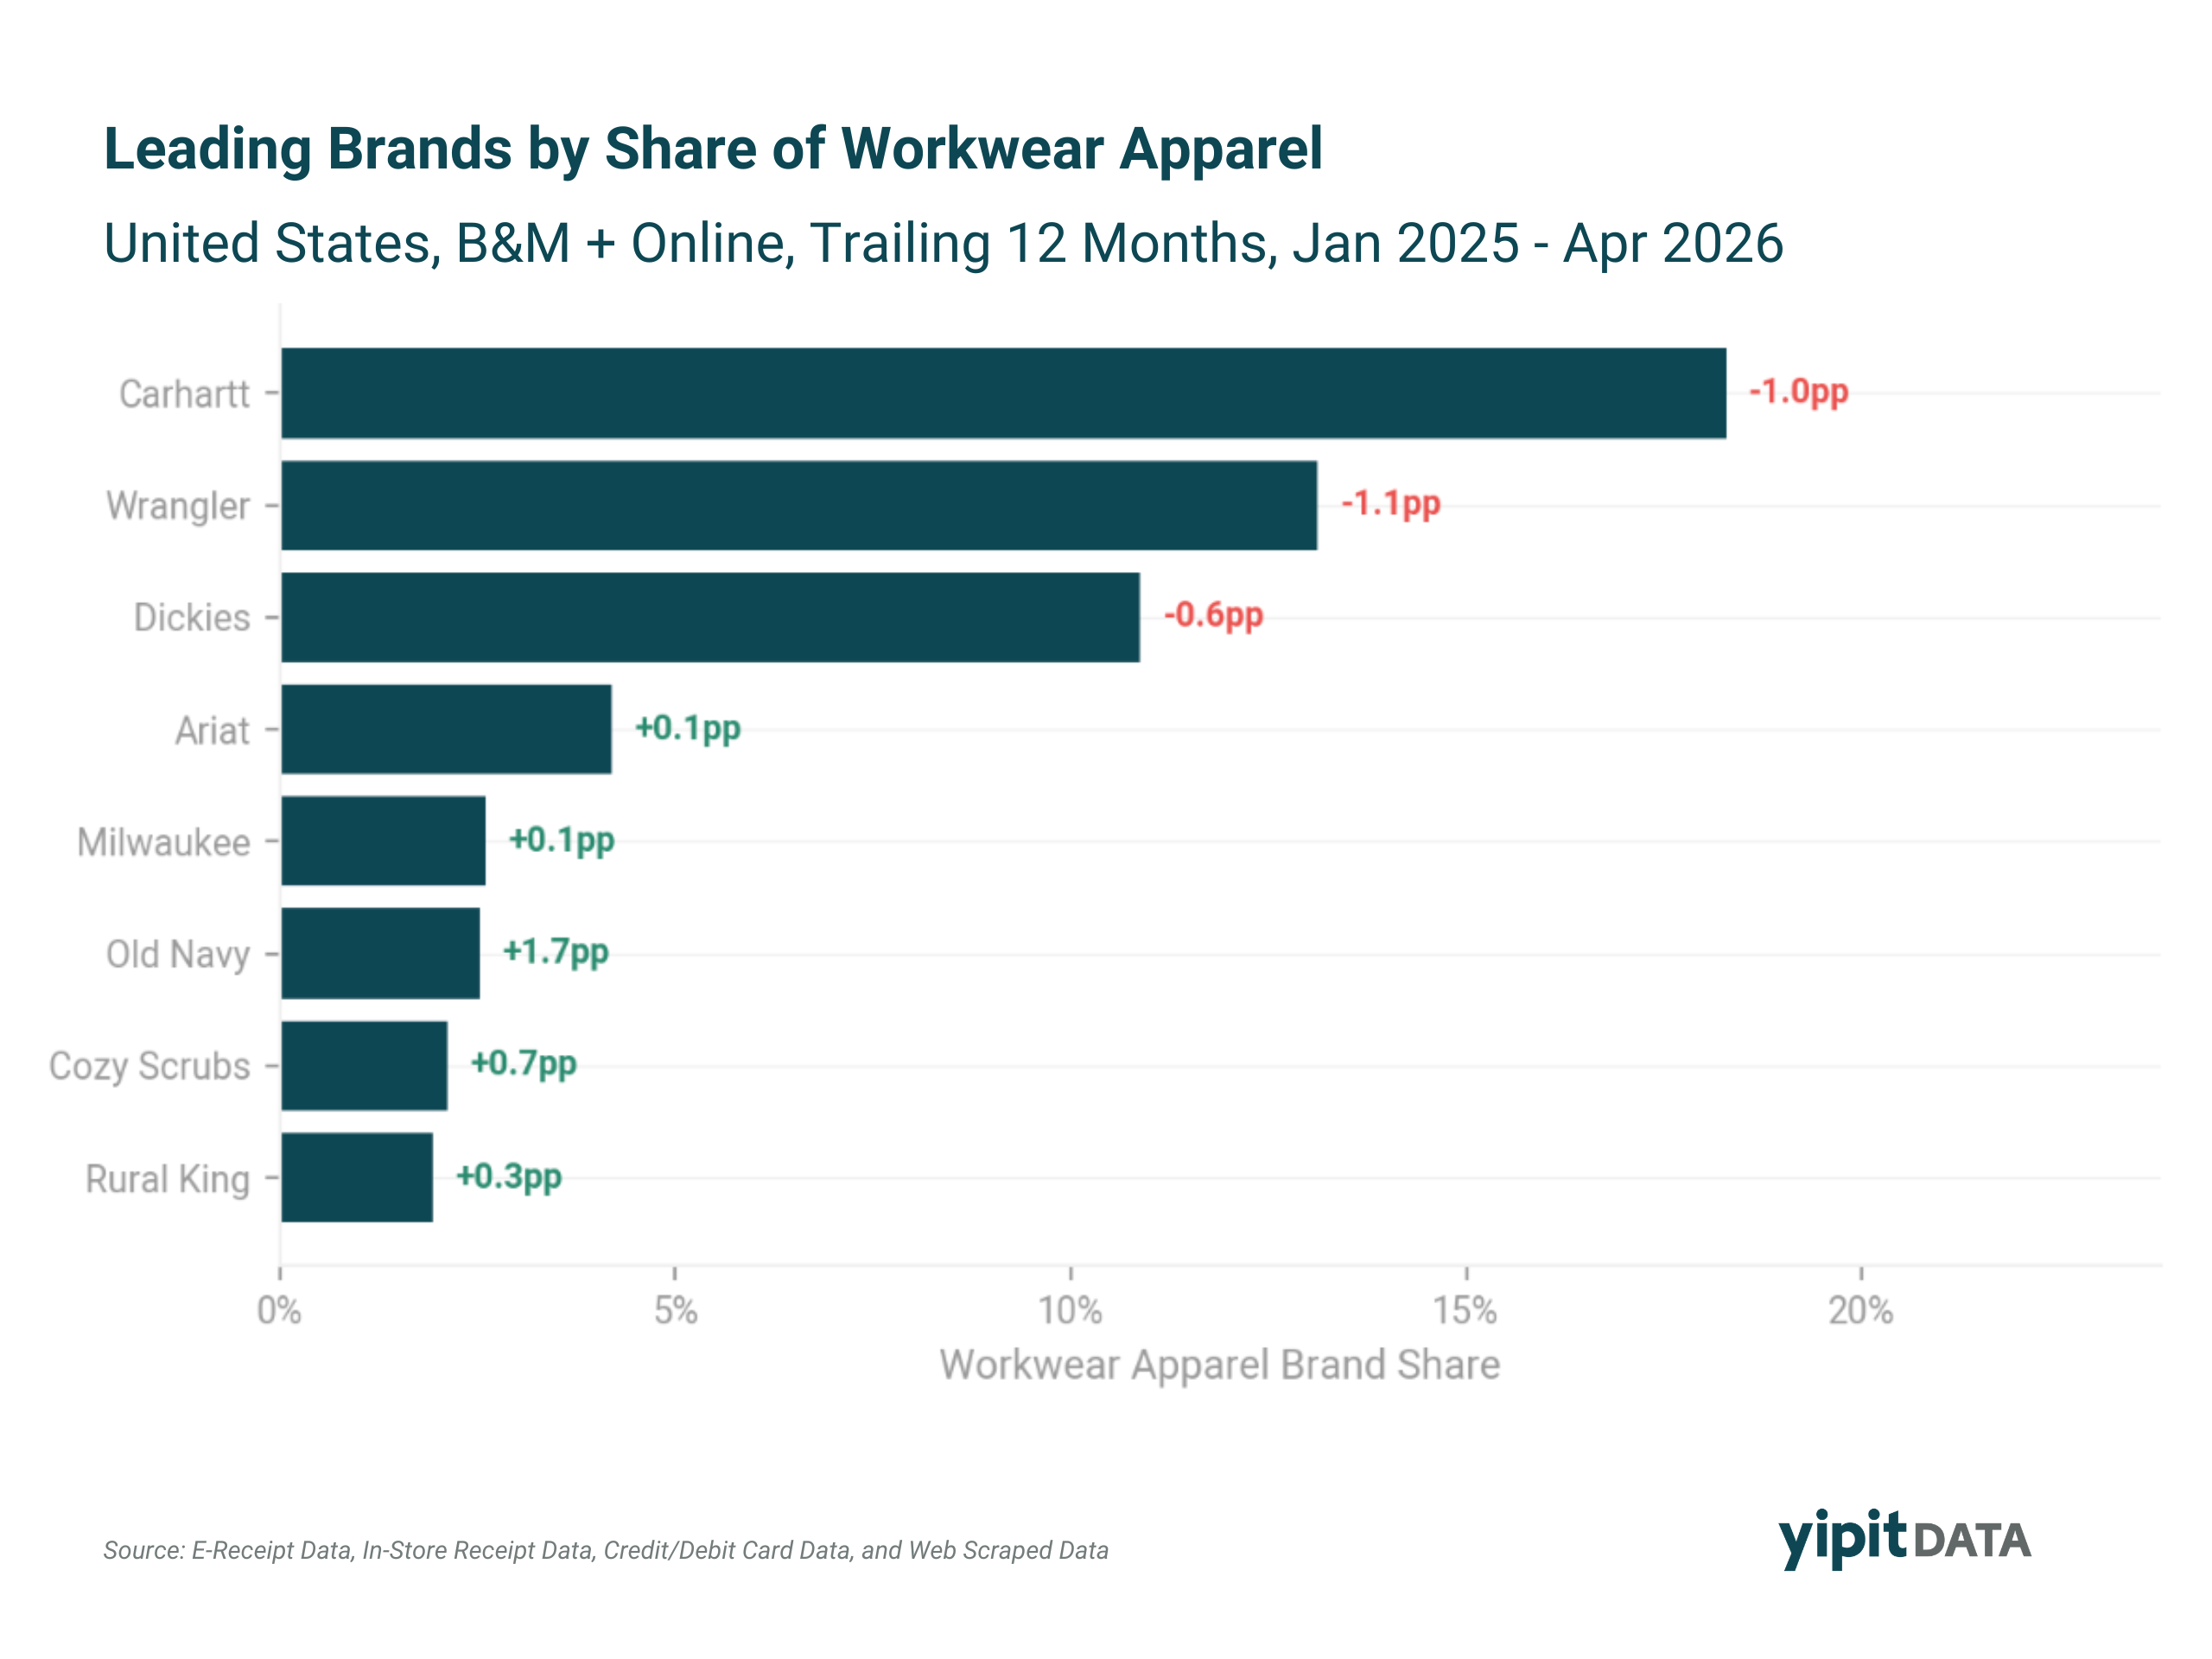
- Old Navy led all workwear apparel brands in share growth, up 1.7ppt YoY, while Carhartt (down 1.0ppt), Wrangler (down 1.1ppt), and Dickies (down 0.6ppt) each lost share over the same period.
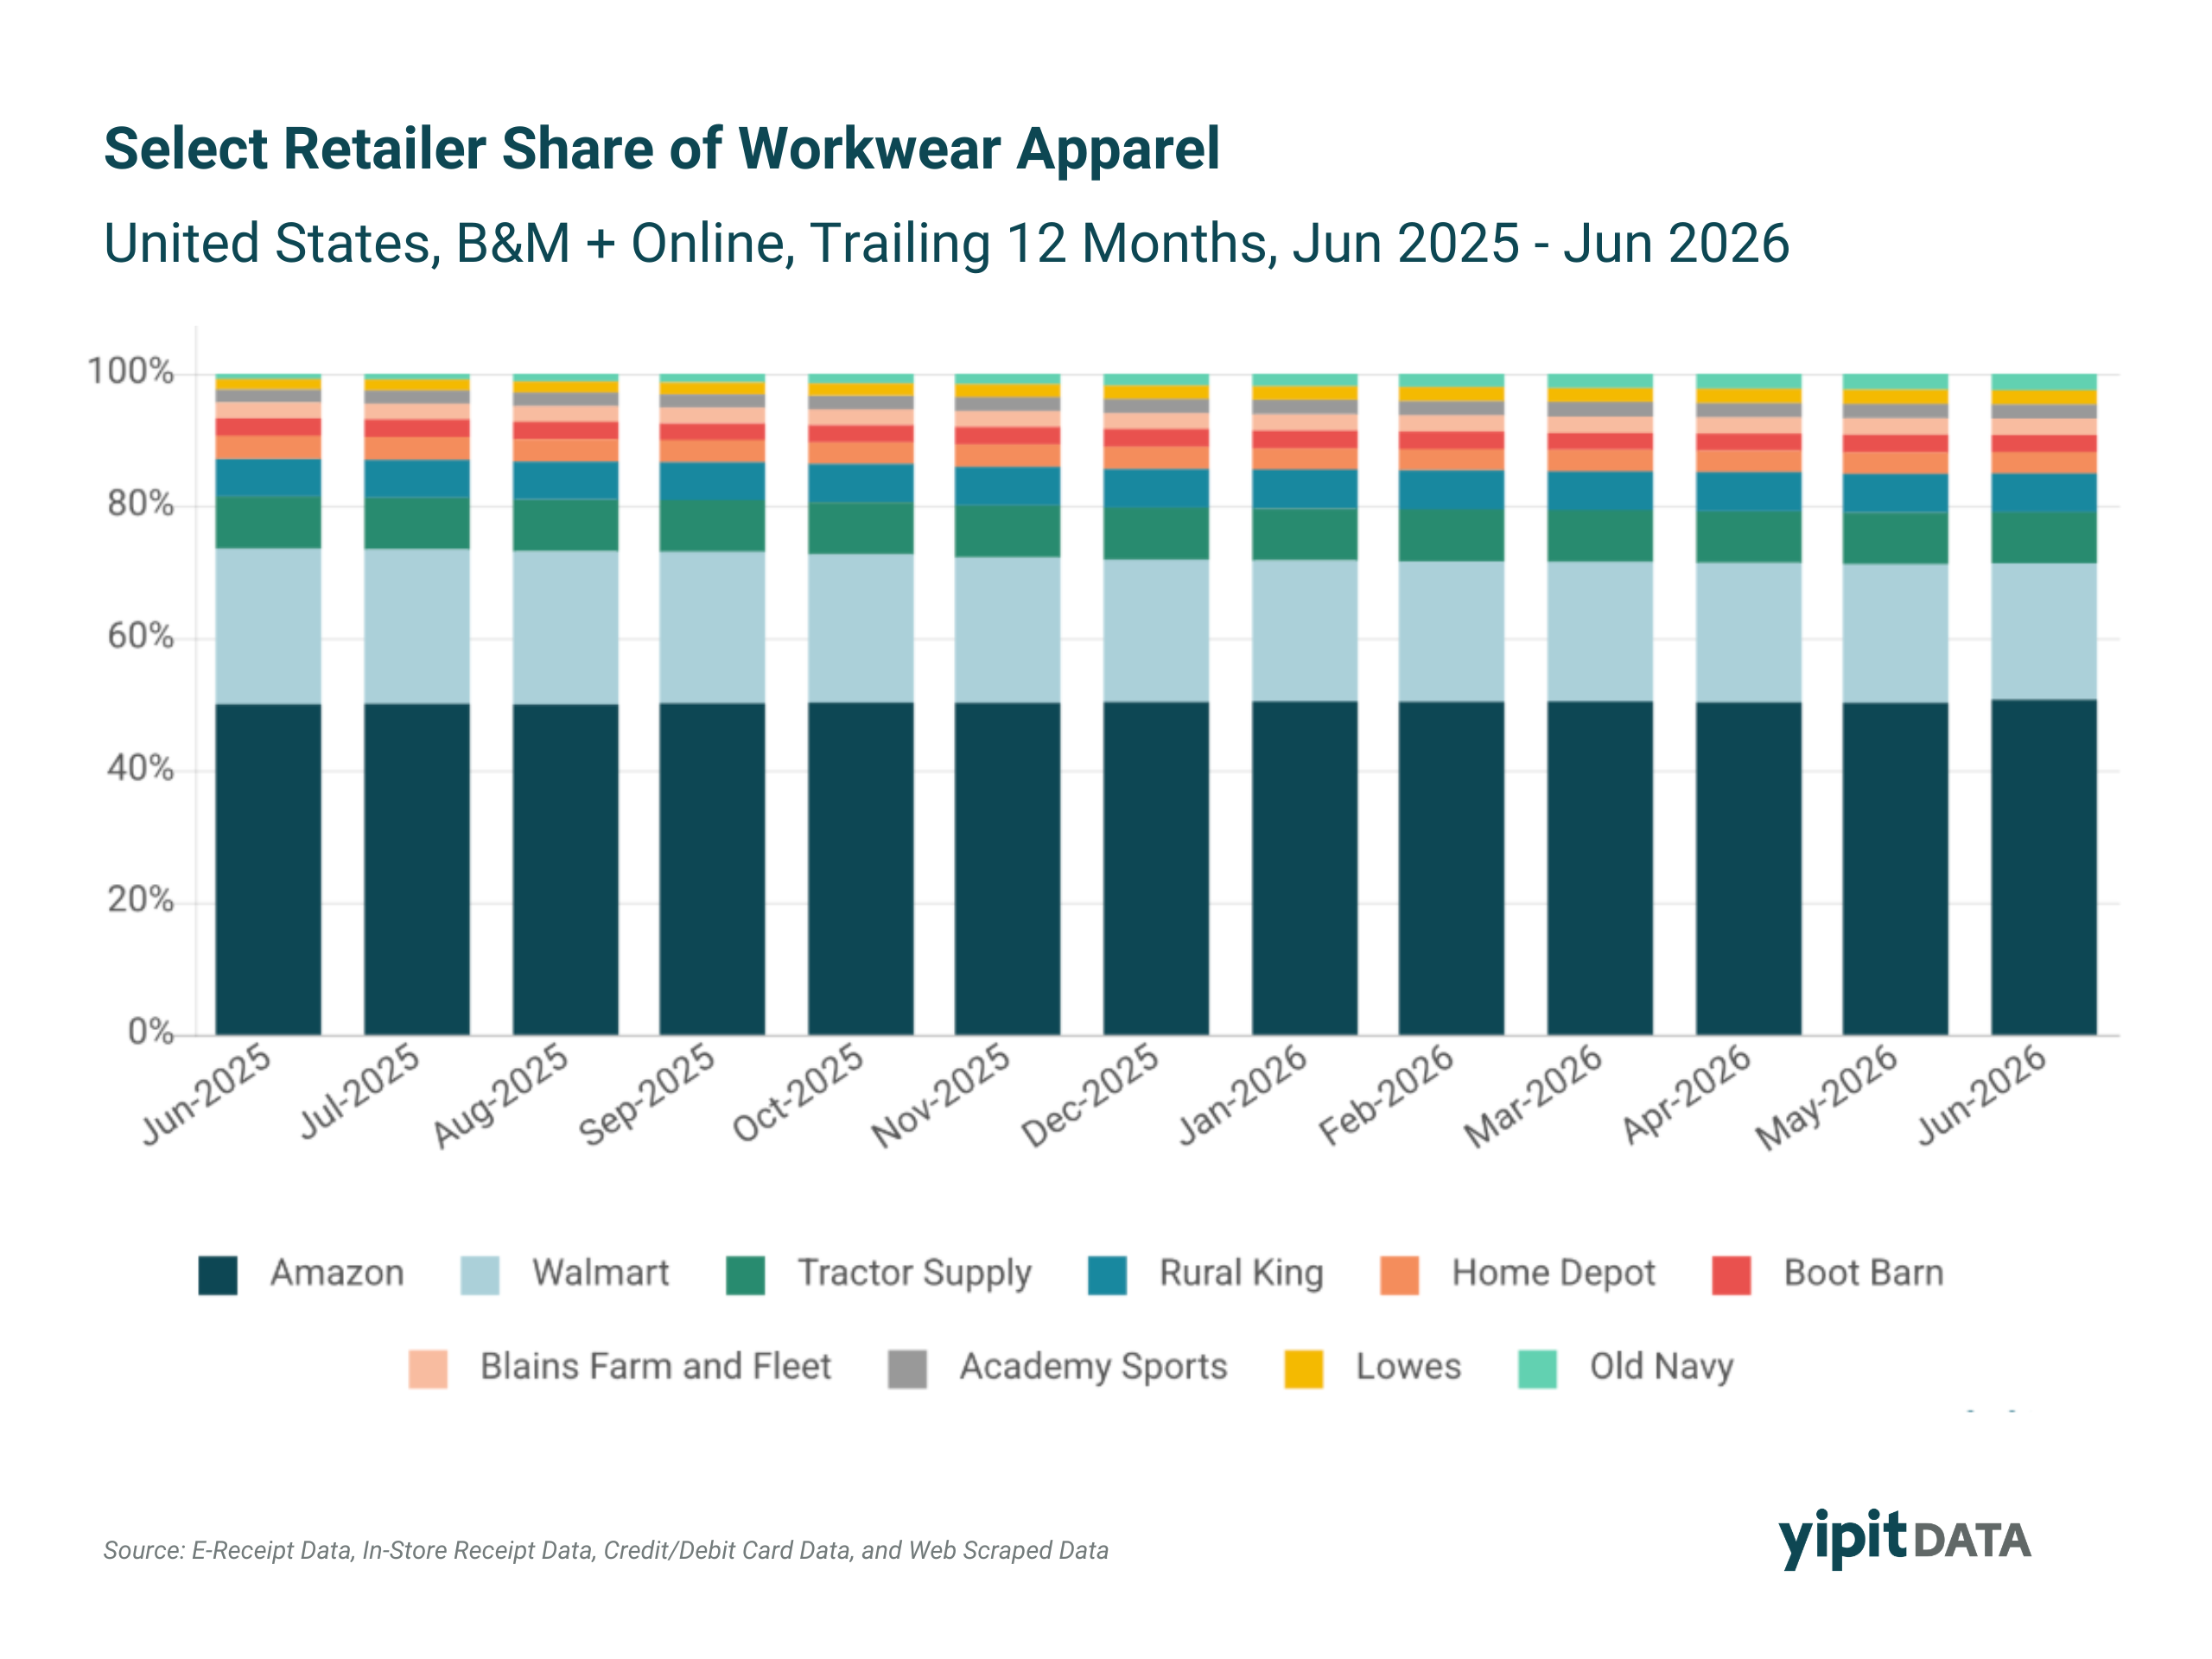
- Amazon, Lowe's, and Old Navy gained workwear apparel retailer share, up 0.7ppt, 0.6ppt, and 1.9ppt respectively, while Walmart declined 3ppt.
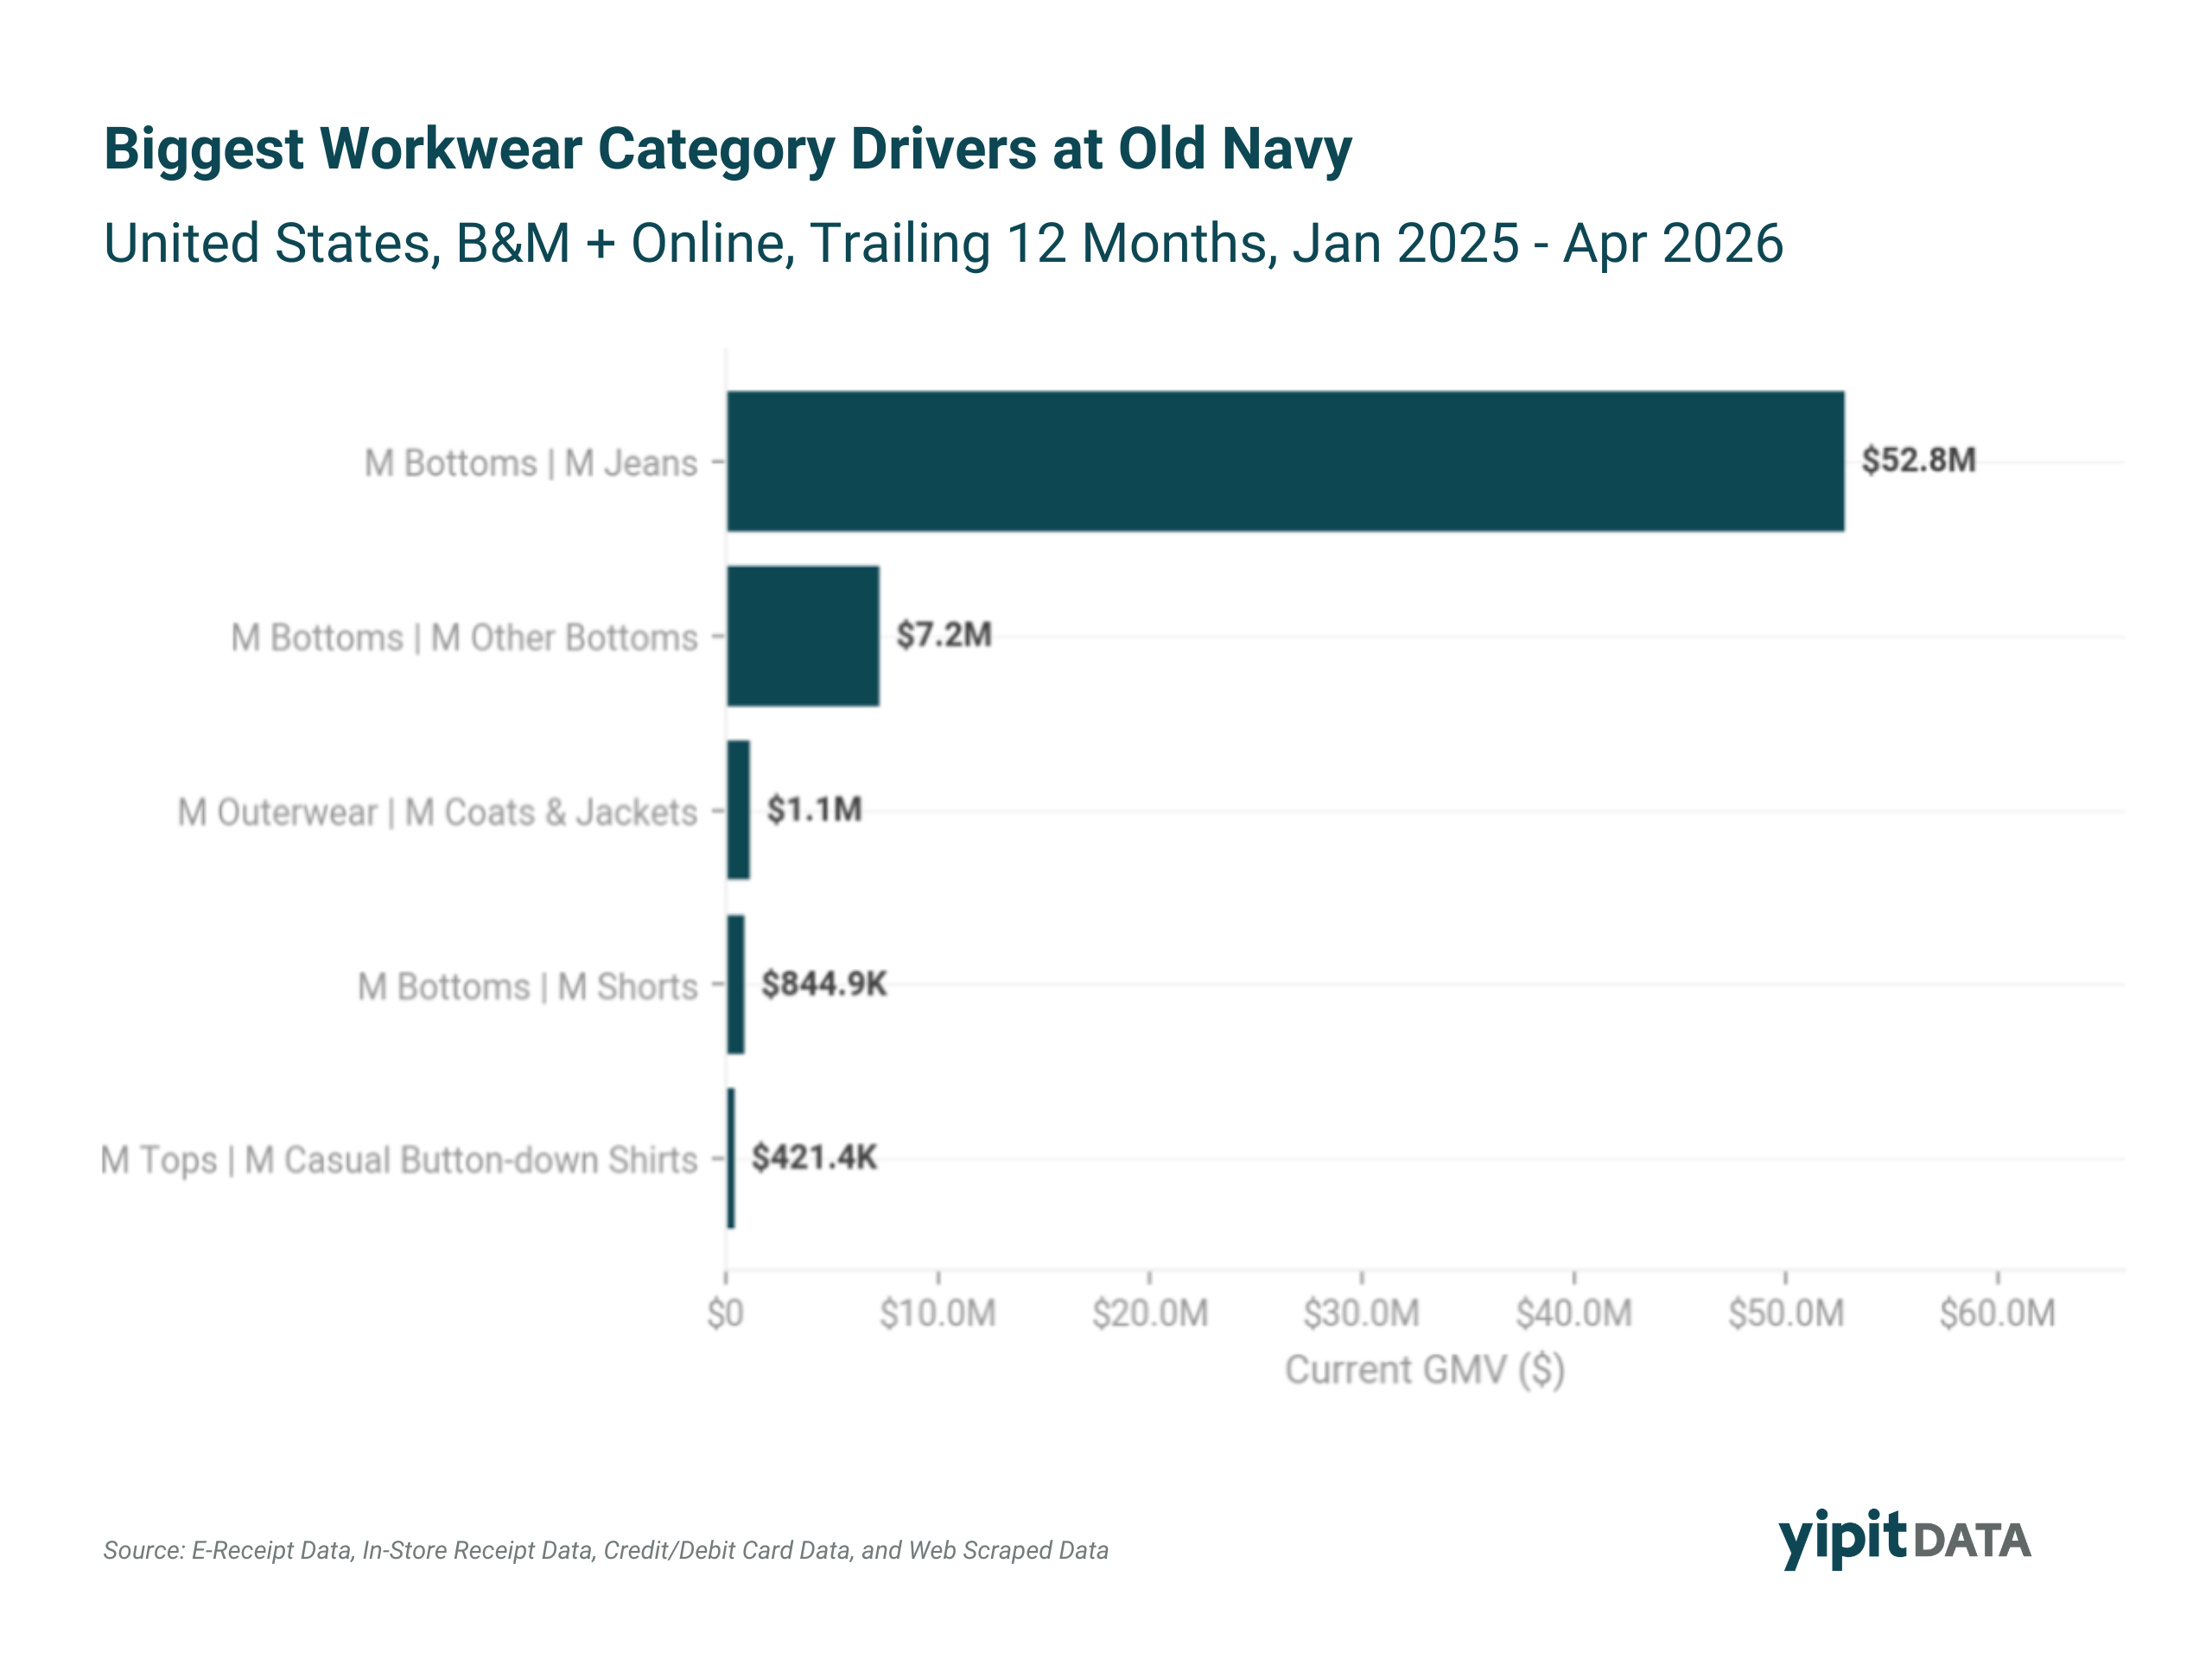
- Men's jeans drove the majority of Old Navy's workwear category growth, generating $52.8M in GMV, more than seven times the size of the next largest contributing category.
Premium Workwear Products Are Outpacing Value and Mid-Market Tiers
Across both workwear apparel and footwear, premium price segments grew faster year over year than value and mid-market segments over the trailing 12 months through June 2026. The trend is most pronounced in footwear, where the premium segment ($150 and above) holds the smallest share of total sales yet posted the fastest growth rate of any price tier. In apparel, where premium is defined as $50 and above, the same pattern holds, premium growth outpaced the lower price bands, though the gap is narrower than in footwear.
This data point matters for brands evaluating where to place new product launches. A smaller, faster growing premium segment suggests room for upside, particularly in footwear, where premium demand has not yet reached the scale seen in apparel.
Amazon, Lowe's, and Old Navy Are Gaining Workwear Apparel Share
Looking at retailer level share of workwear apparel over the trailing 12 months (June 2025 through June 2026), three retailers stand out for gains: Old Navy added 1.9 percentage points (ppt), Amazon added 0.7ppt, and Lowe's added 0.6ppt. Walmart lost the most ground, down 3ppt over the same period.
The pattern points to workwear apparel demand spreading beyond the retailers traditionally associated with the category (home improvement and farm and ranch chains) and into general merchandise and value apparel retailers. Old Navy's gain, in particular, signals that casual retailers are becoming a bigger part of how consumers shop for workwear style apparel.
Carhartt, Wrangler, and Dickies Lose Ground to Old Navy and Cozy Scrubs
Brand level data tells a related story. The three largest workwear apparel brands, Carhartt, Wrangler, and Dickies, each lost share over the trailing 12 months (Carhartt down 1.0ppt, Wrangler down 1.1ppt, Dickies down 0.6ppt). Meanwhile, Old Navy led all brands in share growth (up 1.7ppt), followed by Cozy Scrubs (up 0.7ppt).
This data shows a shift in share away from brands historically built around functional, on the job workwear and toward brands positioned around casual and value oriented styling. It does not indicate that established workwear brands are underperforming in absolute terms, only that their share of the category is being redistributed as more casual alternatives enter consumers' consideration set.
Old Navy's Workwear Growth Is Concentrated in Men's Jeans, Not Technical Gear
Digging into what is actually driving Old Navy's share gain reveals a specific pattern: men's jeans account for the majority of the brand's workwear category growth, generating $52.8M in GMV, more than seven times the size of the next largest contributing category.
This detail is important context for the retailer and brand share trends above. Old Navy's workwear growth is not coming from technical or protective gear, the categories most associated with functional workwear. It is coming from casual bottoms. For anyone tracking workwear brand market share, this is a useful distinction between demand for workwear styled apparel and demand for workwear functionality.
Ariat and Timberland Lead Workwear Footwear Brand Growth
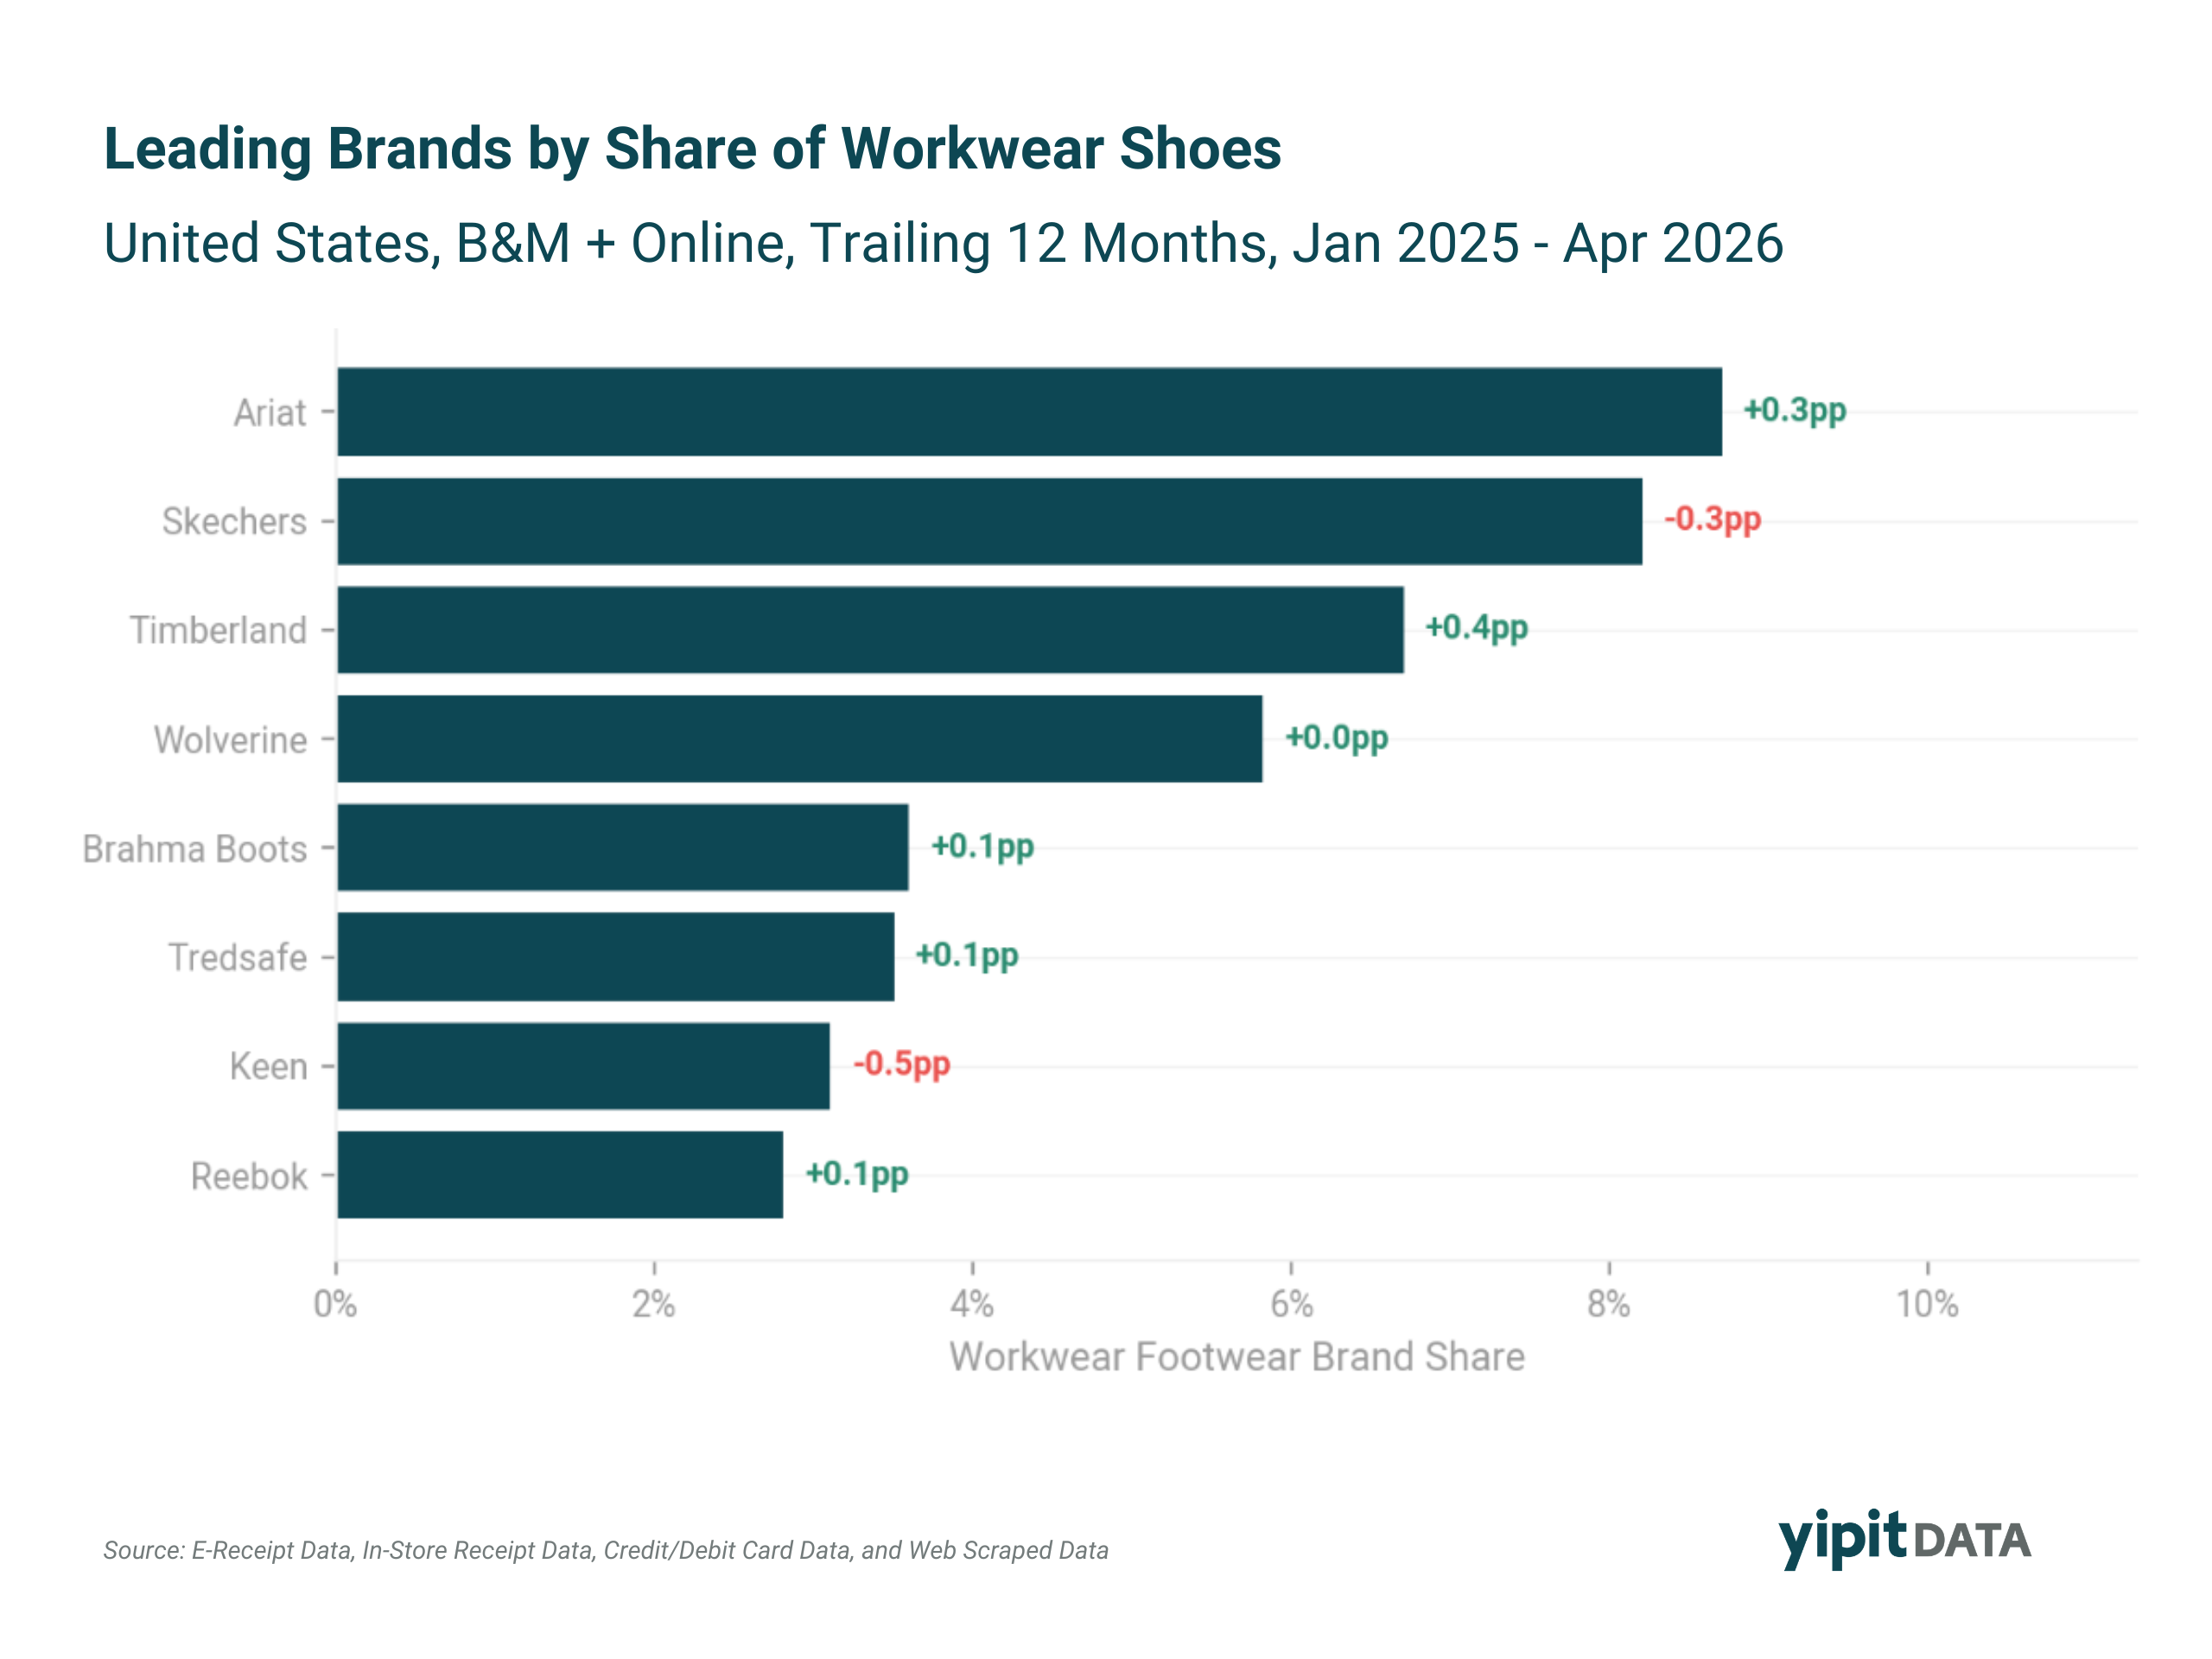
On the footwear side, Ariat (up 0.3ppt) and Timberland (up 0.4ppt) posted the strongest year over year share gains among workwear footwear brands over the trailing 12 months (January 2025 through April 2026). Keen (down 0.5ppt) and Skechers (down 0.3ppt) saw the largest declines.
Given that Amazon is simultaneously growing share of workwear shoes overall, the resilience of Ariat and Timberland suggests that style forward boot brands may carry stronger brand loyalty among workwear footwear shoppers, making them comparatively less exposed to the trade down behavior benefiting marketplace retailers.
What This Means for the Apparel Industry
The 2026 workwear data shows a market splitting in two directions at once, premium pricing gaining ground faster than value tiers, especially in footwear, while casual, value oriented retailers and brands, Old Navy chief among them, pull share from legacy workwear specialists on styling appeal rather than function. This distinction matters for pricing, assortment, and retail partnership decisions, and surfacing it by retailer, brand, and price tier is exactly the kind of granular visibility YipitData's retail and consumer data provides on an ongoing basis.
Methodology
This research is based on YipitData's consumer transaction data, including e-receipt data, in-store receipt data, credit/debit card data, and web-scraped retailer data. This analysis covers the United States workwear apparel and footwear categories across online and brick-and-mortar retail channels for the trailing 12 months through June 2026, with footwear brand share data covering January 2025 through April 2026.
YipitData provides near real-time consumer transaction data and analytics across retail, consumer goods, and e-commerce. For more insights on apparel industry trends, brand performance, and category-level spending analysis visit yipitdata.com.

Speak to our Insights team


