Is “K” the Right Letter for Home Improvement? What I Shared at the HIRI Summit
Published
Oct 21, 2026
Last updated
October 21, 2026
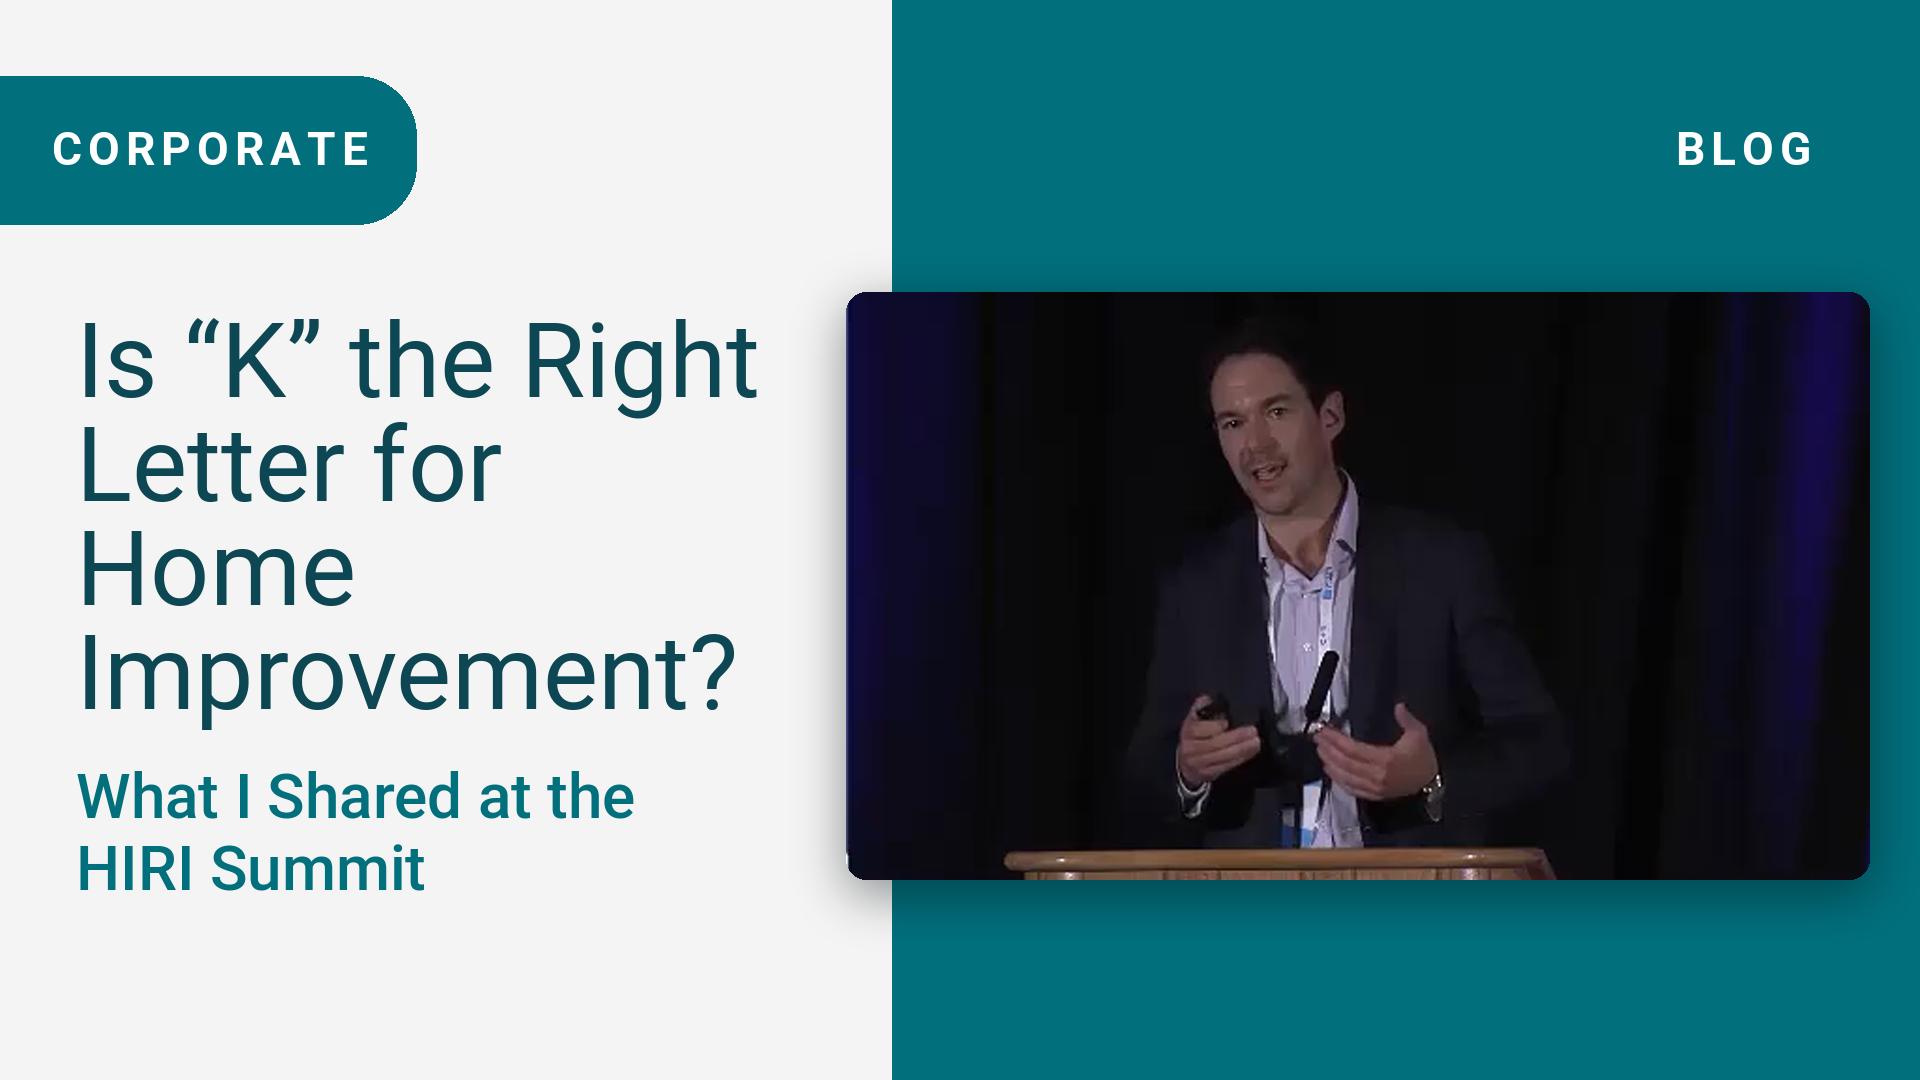
YipitData’s Tyler James recaps his talk at the 2026 HIRI Home Improvement Insights Summit, where he tested the “K-shaped economy” narrative against 12 million shoppers’ receipts. The short version: lower-income households haven’t materially pulled back on home improvement spending, but they are shifting how they shop. The more important income story is where shopper behavior inflects. Around $100K in household income is the new pivot point, where missions shift from replenishing essentials and addressing immediate repair and maintenance needs to more targeted project journeys. Layering in category, sub-category and minor-category trends adds the critical context brands and retailers need to complete the story. Full presentation embedded.
I had the privilege of taking the stage at the HIRI Home Improvement Insights Summit, and I’m still thinking about the conversations that followed. If you were in the room, thank you for sticking with me through ten minutes between you and a long-awaited break, and for indulging my attempt to work through the alphabet. If you couldn’t make it, the full session is below, and I’ll walk through the highlights here.
Why does the “K-shaped economy” need a closer look in home improvement?
Of all the macro trends we’re inundated with, the K-shaped economy might be the most repeated and the least tested. It has become shorthand for a simple story: lower-income shoppers have cut spending and are only looking for the cheapest option, so growth lives and dies with higher-income households. It’s a big statement that “feels right” to a lot of us, but how do we action against the trend if we can’t contextualize it?
At YipitData we sit on a receipt panel of more than 12 million shoppers covering in-store and online purchases across Home Depot, Lowe’s, Amazon, Walmart, Menards, Tractor Supply and Ace Hardware, to name a few. That let us layer in the context the topline read masks about income dynamics. Is home improvement different from true discretionary sectors? Does Kitchen & Bath see the same trends as Building Materials? What about battery-powered string trimmers vs. gas-powered string trimmers? The answer turned out to be more interesting than the headline.
Have lower-income households stopped shopping home improvement?
Buy rates by income cohort are almost exactly where they were in 2023, the first year spending normalized after COVID. Households earning under $50K indexed at 90.9 in January to August 2023 and 90.2 in January to August 2026. The $200K+ cohort moved from 106.0 to 108.4. Every cohort in between shifted by about a point.
So are lower-income shoppers nosediving? No. Are higher-income shoppers driving relative growth? Yes. Both halves of the K are in the aisle, but why they’re there and how they define value HAS shifted, which brings me to the part of the talk I enjoyed most.
Where does shopper behavior actually pivot by income?
The real story isn’t about how much more or less different income groups are spending. It’s about where shopper behavior pivots.
At roughly $100K in household income, behaviors show a clear split. When we look at trip frequency and follow-up behavior instead of participation, the pattern looks less like a K and more like an X, with the crossover right around that line.
Below that line, the mantra in the data is “I need this, and I can’t afford to get it wrong.” Those shoppers are consolidating trips, combining replenishment with reactive repair and maintenance, and doing as much as possible in one visit. They are more DIY-capable than they get credit for and, somewhat to my surprise, a bit more brand loyal. Why? Because a failed purchase means a second trip they didn’t budget for and can’t afford.
Above the line, it’s “it disrupts the whole project if I get it wrong.” These shoppers are increasingly engaged in sequenced, project-based shopper missions that unfold over several weeks: a kitchen and bathroom remodel, a full backyard revamp across landscaping and gardening, lighting, and patio. This group’s shopper journeys are broad, multi-stage… and disruptive. For them, getting a purchase wrong means slowing down the whole project, an error they don’t have time for.
Same store. Same aisles. Two completely different missions.
Which home improvement categories skew to lower- and higher-income households?
Index each category group by income and a clear shape emerges. Households under $50K over-index on needs-based, functional categories like Cleaning (109), Outdoor Power Equipment (103) and Lumber (102). Paint and Tools sit in the middle, shopped roughly evenly by everyone. And $200K+ households over-index on whole-space upgrade categories: Electrical (112), Seasonal & Outdoor (108), Kitchen & Bath (107).
Why isn’t category-level data enough?
Well, here’s what the data tells us. 53% of home improvement sub-categories have an income structure that diverges from their parent category by more than 10 index points. If you’re planning assortment, pricing or messaging for Kitchen & Bath or OPE at the category level, you’re working from the wrong picture about half the time before you start. The home improvement industry trends that make it into a topline deck are real, but the actionable version of them lives one or two levels down.
And the assumption that lower-income shoppers only buy the cheapest option doesn’t hold either. In 68 sub-categories, households under $100K over-index on the top price tier more than $150K+ households do. Almost all of those are functional products. They aren’t trading up for bells and whistles; they’re paying for the product that gets the job done better, for longer, the first time.
Which brands are winning across every income cohort, and how?
I closed with three premium-priced brands that are winning across all income groups: Scotts Miracle-Gro in Lawn & Garden, BEHR in Paint, and RYOBI in Outdoor Power Equipment. There are plenty of cheaper alternatives to each of these brands, but they’re winning through a shared theme: communicating the right value, the right way, outweighs price. Scotts positions against the cost of failure with proven, tested claims. BEHR positions against the cost of rework with durability and cleanability that lasts for years. RYOBI positions against the cost of leaving the ecosystem: one battery, 85+ products, enough to mow half an acre. Each brand understands its project pain points, the role its category plays in causing or alleviating those pain points, and positions its products as a safeguard against that pain.
Their key message? “Pay up now to avoid regret later.” That message lands with a lower-income household fixing a leak they can’t afford to fix again in two months, as well as a higher-income household where picking the wrong sink would extend the kitchen remodel by weeks or months of rework.
What did I take home from the HIRI Summit?
Beyond the data, the thing I appreciated most about the Summit was the quality of the hallway conversations. The questions I got afterward were sharp and practical: how the pivot shifts by region (a $100K household in rural Minnesota is not a $100K household in New York), how trade professionals from lower-income cohorts fit into higher-income projects, and how retailer assortments and their various shoppers alter the story. Those are exactly the layers we’re excited to continue to unpack, and they’re a good reminder that industry trends only become useful once you can view them through the lens of your specific shoppers, categories and retailers.
My one-line summary from the stage still holds: “K” is the first letter in a longer sentence. Shopper behavior does diverge by income, but the blanket version of that story misses what’s happening below the surface, which is exactly where share is won or lost today.
Thank you to the HIRI team for the stage and for another great event, and to my fellow attendees for the engaging conversations around how they can apply these insights to their businesses. If you have questions about anything in the session, want to discuss what these trends look like for your specific categories and brands, or just want to compare notes on what you’re seeing, fill out the form to the right and I'll reach out. I’d love to continue the conversation.
Frequently Asked Questions
Is the K-shaped economy real in home improvement?
Partly. Relative spend does rise with household income, and $200K+ households are the clearest premium, project-driven cohort. But participation hasn’t split: the buy rate index for households under $50K was 90.9 in Jan–Aug 2023 and 90.2 in Jan–Aug 2026, and every cohort moved within about a point except $200K+ (106.0 to 108.4). The K describes motivation, not whether people are shopping.
At what household income does home improvement shopping behavior change?
Around $100K. Below that, shoppers consolidate trips and buy for repair, maintenance and replenishment (“I need this and I can’t afford to get it wrong”). Between roughly $100K and $150K, missions shift toward smaller DIY and aesthetic upgrades. Above $150K, trips become sequenced, multi-week project journeys (“it disrupts the whole project if I get it wrong”).
Which home improvement categories do higher-income households buy most?
Relative to other cohorts, $200K+ households over-index on whole-space upgrade categories: Electrical (112), Seasonal & Outdoor (108), Kitchen & Bath (107) and Lawn & Garden excluding OPE (107), where 100 is the average income cohort. Households under $50K over-index on needs-based categories such as Cleaning (109), Outdoor Power Equipment (103) and Lumber (102). Paint and Tools are shopped roughly evenly across income.
Do lower-income shoppers only buy the cheapest home improvement products?
No. In 68 sub-categories, households earning under $100K over-index on the top price tier more than households earning $150K+ do. Most of those sub-categories are functional products, where a better product avoids a repeat purchase. Brands like Scotts Miracle-Gro, BEHR and RYOBI lead their categories across every income cohort with premium products by positioning on functional utility rather than price.
Why isn’t category-level data enough to understand home improvement shoppers by income?
Because 53% of home improvement sub-categories have an income structure that diverges from their parent category by more than 10 index points. A category that skews higher-income can contain sub-categories that skew lower-income, and the reverse, since the shopper’s mission sets the income mix rather than the aisle. Planning assortment, pricing or messaging at the category level is wrong about half the time before the work starts.

Connect with us!